Is Gutter Cleaning Covered by Homeowners Insurance?
By Flag Gutter · October 20, 2026 · 3 min read
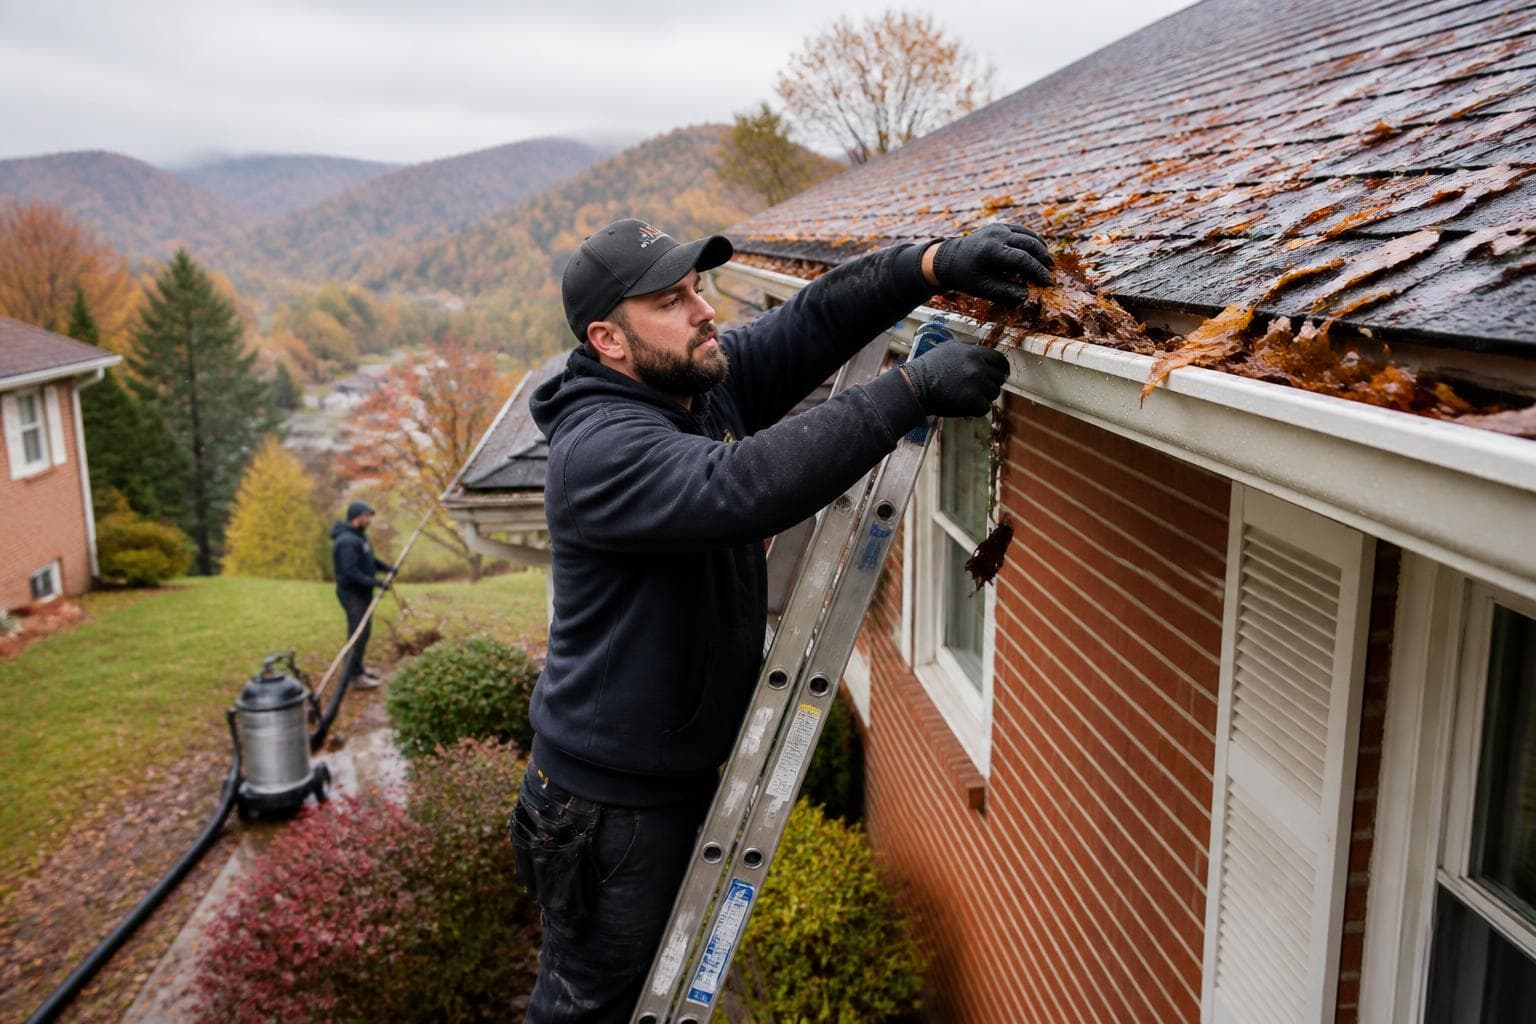
Routine gutter cleaning is generally a homeowner maintenance expense, rather than a benefit under standard homeowners insurance. A claim for damaged gutters is a separate question: payment depends on the policy and the circumstances of the loss.
The National Association of Insurance Commissioners' consumer guide explains that homeowners insurance is not a maintenance contract. Do not assume that having a policy will pay for ordinary cleaning or for deterioration that maintenance would have addressed.
Cleaning and damage are different questions
Use these questions to explain what you need to your insurer:
| Situation | What to ask |
|---|---|
| Leaves need removing from otherwise working gutters | Is there any maintenance benefit or separate service agreement? |
| A storm appears to have damaged a gutter run | Does my policy cover this cause of loss, and what conditions apply? |
| There is long-standing staining or deterioration | Which exclusions apply, and what information is needed to assess the cause? |
| A cleaning visit caused accidental damage | Who should receive the report, and which policy needs to be reviewed? |
An event date alone does not prove a loss is covered. Photos and maintenance records are useful information, but they do not guarantee approval.
What changes the answer for damaged gutters?
Coverage, exclusions, limits, deductibles, and settlement terms matter. Wind or hail damage may be covered under a policy that insures those perils, but coverage is not automatic for every storm-related problem.
The NAIC guide also explains differences between replacement-cost and actual-cash-value coverage. Ask your insurer how your policy would value a covered loss and what deductible would apply.
Questions about interior water damage should be assessed separately. Do not assume an answer about gutter repair also determines coverage for every other affected part of the home.
What to do if you notice damage
The West Virginia Offices of the Insurance Commissioner's property claims guide describes reporting damage, working with an adjuster, and understanding settlement decisions.
From a safe location, record what you observed and when. Photograph visible damage without climbing or standing below loose components. Contact your insurer or agent promptly for reporting instructions and policy-specific deadlines; do not wait for a completed contractor estimate if notice is required sooner.
Keep correspondence, estimates, and receipts. Ask what reasonable steps are needed to prevent further damage and arrange qualified help for work you cannot perform safely. Your insurer can explain how to document temporary repairs and what it needs before permanent work proceeds.
If an accident happens during cleaning
Report the incident to the contractor and seek appropriate assistance for anyone injured. Contact your own insurance professional for guidance about notification and the policies that may be relevant.
Do not assume a contractor's certificate of insurance guarantees that a particular accident is covered or automatically removes every homeowner liability concern. Ask for current insurance information before the job and direct coverage questions to the insurer or agent.
When you need help understanding an insurance response
Ask the insurer to explain its decision and the policy terms it relied on. The West Virginia Offices of the Insurance Commissioner's Consumer Services team provides help with homeowners insurance questions and a complaint process.
Flag Gutter can describe proposed gutter work in a written estimate. We do not determine what your insurer will cover or promise a claim outcome.
Plan cleaning as part of home maintenance
Discuss a cleaning and inspection schedule that suits your tree cover, roofline, and conditions. There is no universal number of cleanings that guarantees insurance coverage. Our local cleaning guide offers questions to discuss during a visit.
For gutter cleaning or repair in Southern West Virginia, request a free written estimate. If the work relates to a possible claim, ask your insurer what documentation it needs.